
Manufacturing has spent decades progressing from mechanized equipment to programmable robots that perform tightly defined tasks with exceptional precision. Physical AI extends that model by combining perception, learned models and adaptive control, potentially allowing machines to handle conditions that cannot be fully specified beforehand. Conventional automation remains highly effective when engineers can structure a process around the machine; embodied intelligence seeks to make machines useful where processes contain more variation.
Unitree built much of its international profile with robots that could run, dance and perform increasingly difficult physical movements, but its August 2026 Shanghai initial public offering moved the economic story beyond demonstration videos. The Chinese robotics company priced the offering at a valuation of roughly $9 billion, seeking about $904 million after 2025 revenue more than quadrupled to nearly 1.7 billion yuan. Humanoids had overtaken quadruped machines as its largest product category.
DeepSeek’s $20.8 million investment brought another part of China’s technology economy into the same story. The companies agreed to collaborate on artificial intelligence models, motion control and embodied intelligence, joining lower-cost robotics hardware with AI designed to perceive and act in the physical world. Large-scale physical-world training data remains a central bottleneck between impressive humanoid movement and reliable autonomous work.
As robots become connected computing systems, that transition also gains an internet dimension. Remote monitoring, shared models and fleet-management software can allow information gathered during operation to improve machines beyond a single production line. The potential economic change is not merely smarter machinery. Factories themselves can become connected environments for generating and applying machine intelligence.
China enters that transition with something that cannot be created by training a better model alone.
From Industrial Automation to Physical AI
| Model | Operating Logic | Primary Strength | Learning Requirement |
|---|---|---|---|
| Fixed automation | Predefined motion | Speed and precision | Minimal adaptation |
| Connected robotics | Programmed work plus networked control | Fleet coordination | Operational telemetry |
| Physical AI | Perception plus adaptive action | Task flexibility | Physical interaction data |
Sources: International Federation of Robotics, Reuters
China Already Owns the Deployment Environment
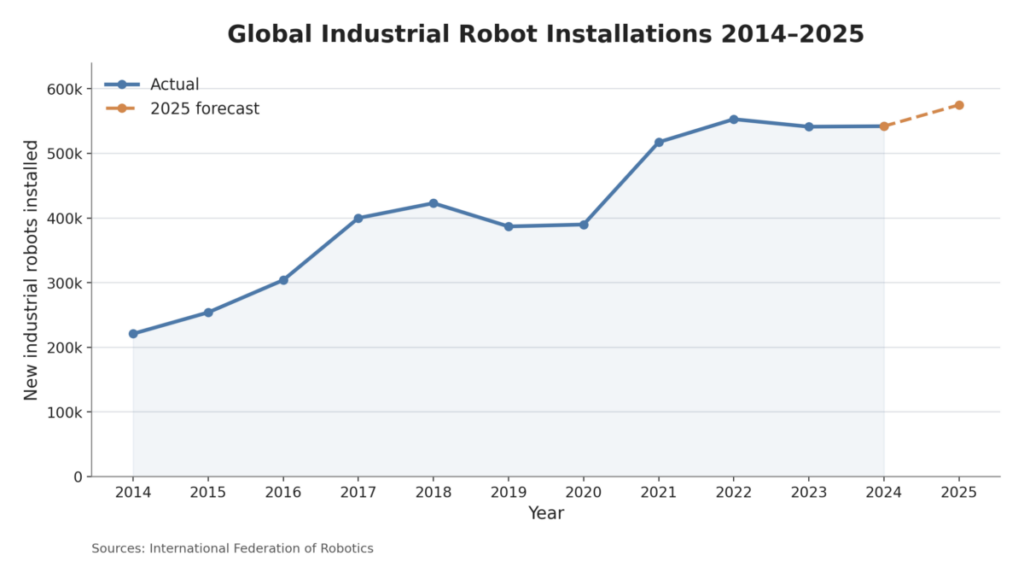
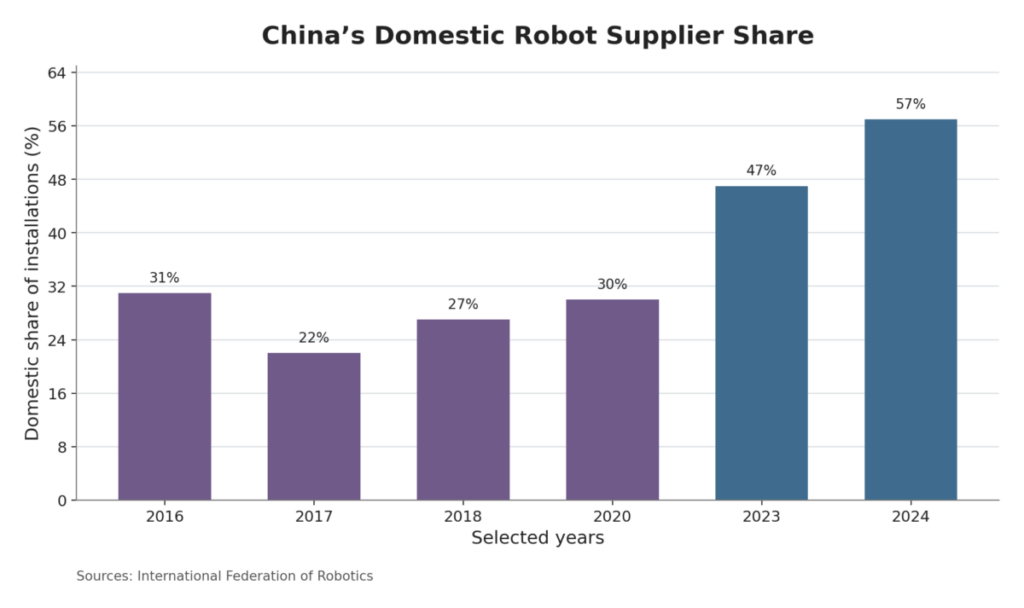
By the end of 2024, China had installed 295,000 industrial robots in a single year, accounting for 54 percent of worldwide installations and setting a national record. More than two million industrial robots were operating in Chinese factories, while domestic manufacturers captured 57 percent of the home market, up from about 28 percent over the preceding decade.
Those numbers matter less as a technological ranking than as evidence of accumulated industrial capacity. Manufacturers already using robotics employ engineers familiar with integration and maintenance, while suppliers serving industrial demand have incentives to improve components and reduce costs. Unitree benefits from the same environment, with China’s competitive humanoids supported partly by increasingly deep and self-sufficient manufacturing supply chains.
A robot becomes economically significant only after a manufacturer can insert it into production, expose it to operating conditions and determine whether it reduces the cost of useful work. China possesses an unusually large number of places where those experiments can occur, from electronics to automotive manufacturing. Industrial concentration can therefore reinforce technological development without requiring every Chinese robotics company to lead every technical category.
Policy has amplified that private industrial machinery rather than replacing it. China’s automation expansion has developed alongside national and local strategies to modernize manufacturing, while Shanghai is subsidizing technological transformation and creating demonstration environments for new industrial technologies. Such measures do not prove commercial viability, but they can reduce the early cost of experimentation when private returns remain uncertain.
Together, installed capacity, supplier depth, operating experience and policy support give Physical AI an unusually developed industrial foundation. The next question is not whether China has places to deploy intelligent machines, but whether those deployments can improve the machines themselves.
China’s Industrial Robotics Position in Global Manufacturing
| Indicator | China Position |
|---|---|
| Local supplier share of domestic robot installations | 30% in 2020 → 57% in 2024 |
| Global electronics robots installed in China | 64% |
| Chinese supplier share in electronics | 59% |
| Chinese supplier share in metal and machinery | 85% |
Sources: International Federation of Robotics
Factories Are Becoming Training Environments
Where conventional industrial robotics achieves reliability by controlling uncertainty, embodied intelligence is being developed for tasks where some uncertainty remains. Engineers can specify the movement of a fixed robotic arm with extraordinary precision when components arrive consistently. A general-purpose machine must instead interpret variation in position, force and physical conditions while maintaining production-line reliability.
Learning those capabilities requires data that differs from the text and images that fueled much of generative AI. Robots must experience how objects respond to manipulation and how small changes affect familiar tasks. Simulation can supply part of that experience, but production exposes systems to wear, positioning errors and physical irregularities that synthetic environments may not fully reproduce. Unitree is already using human-guided trials to generate physical-world training data.
Once those machines enter factories, China’s industrial foundation can become a learning mechanism rather than merely a deployment advantage. Factories support repeated physical interaction, producing operating experience that can improve embodied models and make additional automation economically attractive. Connected fleets can extend that cycle by allowing lessons from multiple deployments to influence shared software rather than remain isolated inside individual machines.
Evidence of that transition is beginning to appear on production lines, although it should be treated cautiously. During a six-day demonstration at Longcheer Technology, eight AgiBot humanoids worked on an active tablet-production quality-inspection line for more than 64 hours and handled 17,625 tablets. AgiBot reported a 99.99 percent task-success rate, making the figure a company claim rather than independent proof of mature industrial economics.
Shanghai’s plans indicate how aggressively China intends to test whether such demonstrations can scale. By 2030, the city aims to deploy 100,000 humanoid robots in factories and raise industrial-agent adoption above 80 percent among large industrial enterprises, placing embodied intelligence alongside industrial data and computing systems in its manufacturing strategy. These are targets, not realized outcomes, but they show policy being used to accelerate learning and commercialization.
Manufacturing capacity can consequently become an input into AI development as well as an industry transformed by it.
Factories as Physical AI Training Infrastructure
| Development Indicator | Scale |
|---|---|
| AgiBot training-site operation | About 17 hours per day |
| State humanoid procurement | 4.7m yuan in 2023 → 214m yuan in 2024 |
| Shanghai embodied-AI industry target | More than 50bn yuan by 2027 |
| Shanghai ecosystem target | 100 firms, 100 scenarios, 100 products |
Sources: Reuters, Shanghai Municipal People’s Government
From Cheap Labor to Automation Productivity
China’s automation push is accelerating as one component of its earlier manufacturing advantage becomes less dependable. The national population fell by 3.39 million in 2025 to 1.40489 billion, with 7.92 million births and 11.31 million deaths producing a natural growth rate of negative 2.41 per thousand. Demographic contraction does not translate directly into factory labor shortages, but it strengthens the long-term incentive to use capital more intensively where machines can perform work reliably.
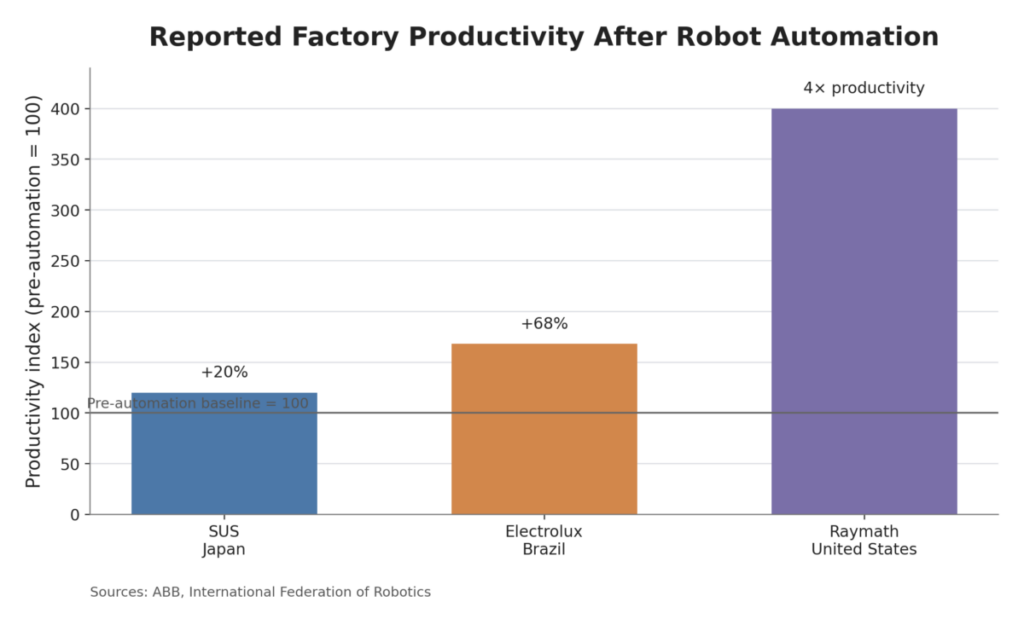
Evidence from conventional robotics shows why that incentive matters. Research on Chinese firms found that robot adoption increased labor productivity by an average of 11.2 percent, total factor productivity by 8.4 percent and profit by 11.5 percent. Employment also increased among adopting firms, illustrating how productive companies can expand even as machines change the composition of work.
Worker-level outcomes are less favorable. An NBER study found that a one-standard-deviation increase in robot exposure was associated with declines of about 1 percent in labor-force participation, 7.5 percent in employment and 9 percent in hourly wages among exposed workers. Firm productivity and individual adjustment can therefore move in different directions, making automation both a growth mechanism and a distributional problem.
Physical AI could extend that adjustment beyond tasks suited to traditional robotics. Existing factories contain equipment and workspaces arranged around human movement, while specialized automation often requires processes to be redesigned around machines. A sufficiently capable humanoid offers the inverse possibility: adapt the machine to an existing environment, expanding automation toward variable work that previously remained uneconomic.
The economic appeal of humanoid form is therefore brownfield compatibility rather than resemblance to a person. Specialized industrial robots will remain superior where repetition rewards speed and precision, but general-purpose machines could matter where flexibility reduces redesign costs. For workers, that would shift some demand toward maintaining, supervising or training automated systems while increasing pressure on routine manual work.
China may ultimately be attempting to graduate from cheap labor without surrendering the industrial ecosystem it helped build. The production equation would shift from labor-cost advantage combined with supply-chain scale toward automation productivity operating within the same supplier networks and production knowledge.
China’s Manufacturing Economics as Labor Conditions Change
| Indicator | 2025 Level or Research Effect |
|---|---|
| Population aged 16–59 | 60.6% |
| Population aged 60+ | 23.0% |
| Total employment | 725.0 million |
| Overall labor productivity growth | +6.1% |
| Hours worked after higher robot exposure | +14% among those remaining employed |
Sources: National Bureau of Statistics of China, National Bureau of Economic Research
Automation May Not Bring the Factory Home
For high-wage economies, automation has long supported a reshoring argument: if machines reduce the labor required to manufacture a product, the wage gap between domestic and offshore production narrows. Proximity to customers and greater supply-chain resilience can then make local production more attractive.
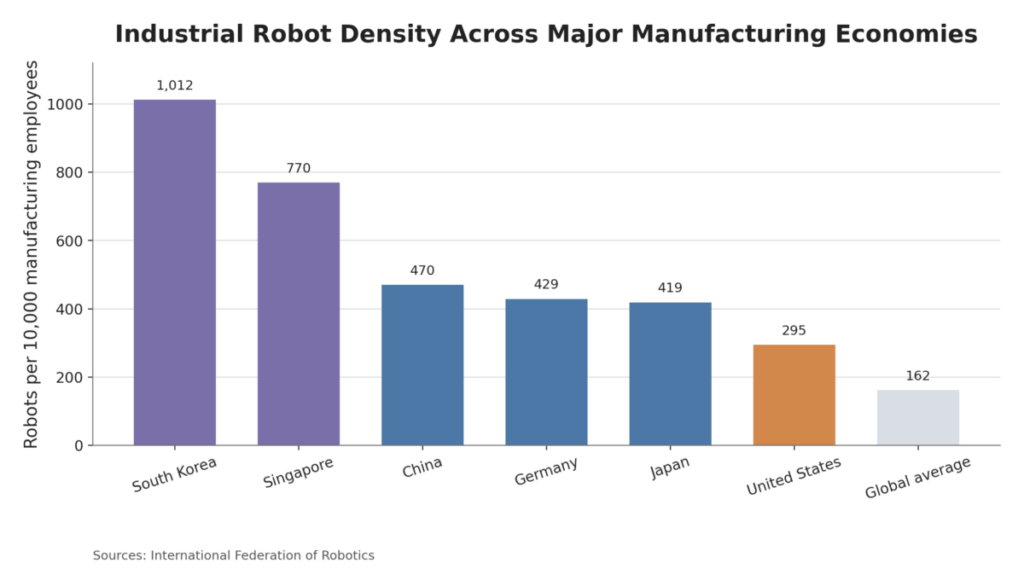
China complicates that reasoning because automation reaches an economy already deploying robots at unmatched scale. Its 295,000 industrial robot installations in 2024 dwarf annual totals in other major manufacturing economies, while the installed base exceeds two million machines. The productivity benefits of new automation therefore arrive alongside existing suppliers, logistics capabilities and accumulated production experience rather than replacing them.
As direct labor becomes a smaller component of manufacturing economics, those non-labor advantages can carry more weight. Supplier proximity shortens coordination cycles, while production knowledge improves the utilization of expensive equipment. Automation may therefore reduce China’s labor-cost disadvantage faster than it reduces the benefits created by decades of industrial clustering.
That shift creates different pressures across manufacturing regions. High-wage economies gain a stronger case for selective reshoring when automation combines with resilience or proximity to customers, while lower-cost challengers such as India or Vietnam face a different calculation. If flexible machines materially reduce labor’s share of production cost, inexpensive labor alone becomes a weaker comparative advantage even as those countries retain other reasons to attract investment.
Geopolitics may further complicate the geography of Physical AI. Unitree has warned that tighter U.S. restrictions could constrain access to an important overseas market, while U.S. regulators have moved to restrict authorization of certain foreign-made advanced robots. If embodied AI becomes critical industrial infrastructure, robotics could face the strategic fragmentation already visible in semiconductors and communications equipment.
Physical AI therefore does not inherently favor China or guarantee reshoring elsewhere. It changes the weighting of labor costs, capital productivity, industrial coordination and market access in determining where production belongs. China begins that recalculation with unusually strong non-labor advantages already in place.
How Physical AI Could Reshape Manufacturing Location Advantages
| Manufacturing Position | Existing Strength | Physical AI Effect |
|---|---|---|
| China | Industrial clustering | May reinforce automation scale |
| High-wage economies | Market proximity | Improves selective reshoring case |
| Lower-cost challengers | Labor-cost advantage | May reduce wage advantage |
| Cross-border robotics markets | Global technology access | Greater regulatory fragmentation |
Sources: International Federation of Robotics, Reuters
The Economics Still Have to Work
Measuring the Economics of Industrial Physical AI
| Measurement | What to Measure |
|---|---|
| Utilization | Productive runtime |
| Reliability | Successful task completion |
| Human dependency | Supervision and intervention |
| Integration burden | Deployment and retraining cost |
| Lifecycle economics | Maintenance and useful life |
| Final benchmark | Cost per successful industrial task |
Sources: Figure AI, International Federation of Robotics, Reuters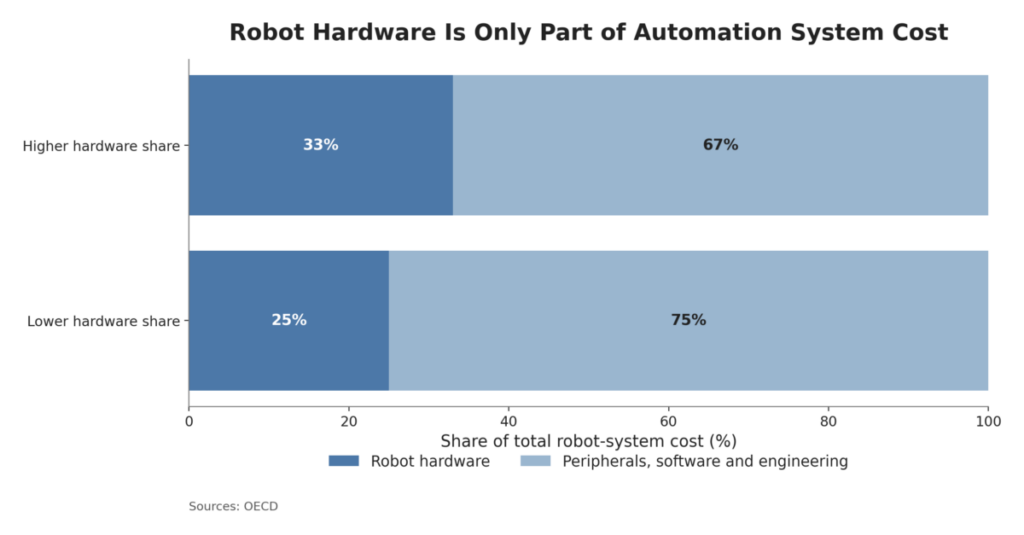
TL;DR Summary
- China installed 295,000 industrial robots in 2024, representing 54 percent of worldwide installations.
- More than two million industrial robots already operate in Chinese factories.
- Chinese manufacturers supplied 57 percent of their domestic industrial robot market in 2024.
- Physical AI extends automation from predefined routines toward machines capable of adapting to changing physical conditions.
- Connected robotic fleets could turn factory experience into training input for shared embodied-AI models.
- AgiBot has already tested humanoids on an operating tablet-production line, although its performance figures remain company-reported.
- Shanghai targets 100,000 humanoid robots in factories and industrial-agent adoption above 80 percent among large industrial enterprises by 2030.
- China’s demographic contraction increases the long-term economic incentive for labor-saving capital investment.
- Chinese firm-level research associates robot adoption with higher productivity and profitability, while worker-level evidence shows meaningful adjustment costs.
- Flexible automation could weaken the importance of low wages without eliminating China’s supplier and industrial-clustering advantages.
- U.S. restrictions indicate that robotics and Physical AI may increasingly develop across competing geopolitical technology ecosystems.
- Humanoid robotics becomes economically disruptive only when its fully loaded cost per successful industrial task competes with labor and specialized automation.
Sources
Manufacturing Is Entering Its Physical AI Phase
- Reuters; Chinese Humanoid Robot Maker Unitree Prices IPO at $9 Billion Valuation; – Link
- Reuters; DeepSeek Invests $20.8 Million in Unitree’s Shanghai IPO; – Link
- OECD; Labour-Saving Technologies and Employment Levels; – Link
- Institute of Internet Economics; Robotics The Next Internet Platform Will Move Things; – Link
China Already Owns the Deployment Environment
- International Federation of Robotics; World Robotics 2025 Industrial Robots; – Link
- International Federation of Robotics; China Makes AI-Powered Robots Core of National Strategy; – Link
- Reuters; Chinese Robotics Firm Unitree Eyeing $7 Billion IPO Valuation; – Link
- International Federation of Robotics; Global Robot Demand in Factories Doubles Over 10 Years; – Link
Factories Are Becoming Training Environments
- Reuters; China’s AI-Powered Humanoid Robots Aim to Transform Manufacturing; – Link
- AgiBot; Six-Day Humanoid Robot Factory Production-Line Demonstration; – Link
- Shanghai Municipal People’s Government; Implementation Plan for the Development of the Embodied Intelligence Industry; – Link
- Shanghai Municipal People’s Government; Shanghai Highlights Development Priorities for Next Five Years; – Link
- Figure AI; Figure 02 Contributed to the Production of 30,000 Cars at BMW; – Link
From Cheap Labor to Automation Productivity
- National Bureau of Statistics of China; Statistical Communiqué of the People’s Republic of China on 2025 National Economic and Social Development; – Link
- Freeman et al.; The Cause and Consequence of Robot Adoption in China; – Link
- The Economic Journal; How Do Workers Adjust to Robots Evidence from China; – Link
- The Review of Economics and Statistics; Robots at Work; – Link
Automation May Not Bring the Factory Home
- International Labour Organization; Robotics and Reshoring Employment Implications for Developing Countries; – Link
- International Labour Organization; Automation Employment and Reshoring Case Studies of Apparel and Electronics; – Link
- International Federation of Robotics; Global Robot Density in Factories Doubled in Seven Years; – Link
- Reuters; Trump Administration Bans New Chinese Humanoid Robots to Protect US AI Buildout; – Link
- Reuters; China’s Unitree Flags US Sales Risk Ahead of Shanghai IPO; – Link
The Economics Still Have to Work
- Reuters; What Is Unitree and Why Are China’s Humanoid Robot Makers Racing to List; – Link
- Reuters; Unitree’s Shanghai IPO More Than 8,000 Times Oversubscribed by Retail Investors; – Link
- OECD; Determinants and Impact of Automation; – Link
- OECD; Making Life Richer Easier and Healthier Robots Their Future and the Roles for Policy; – Link
- ABB; Collaborative Robots Boost Productivity by 68 Percent on Electrolux’s Refrigerator Production Line; – Link
- ABB; YuMi Robots Help Leading Aluminum Profile Manufacturer Increase Production Efficiency; – Link
- International Federation of Robotics; Cobots Boost Production on Welding and Machine Tending at Raymath; – Link
Keywords: Robotics, Manufacturing, Automation, Physical AI, Industrial Economics, Embodied Intelligence, Manufacturing Competitiveness